The Middle East tensions, US interest rates and industrial demand have sent the three major commodities - Oil, gold and silver - along sharply different paths, said an expert.
While oil has largely responded to geopolitical developments, gold has been driven primarily by monetary policy and silver been influenced by both interest rates and demand from industries including solar energy, electronics and artificial intelligence.
Two forces have dominated the market: conflict in the Middle East, which has disrupted physical energy supply routes, and the direction of US interest rates, which affects the appeal of non-yielding assets, remarked Nagham Hassan, Mena market analyst at etoro, a major trading and investing platform.
While oil has largely responded to geopolitical developments, gold has been driven primarily by monetary policy. Silver has been influenced by both interest rates and demand from industries including solar energy, electronics and artificial intelligence, stated Hassan.
Oil tied to developments in the Middle East
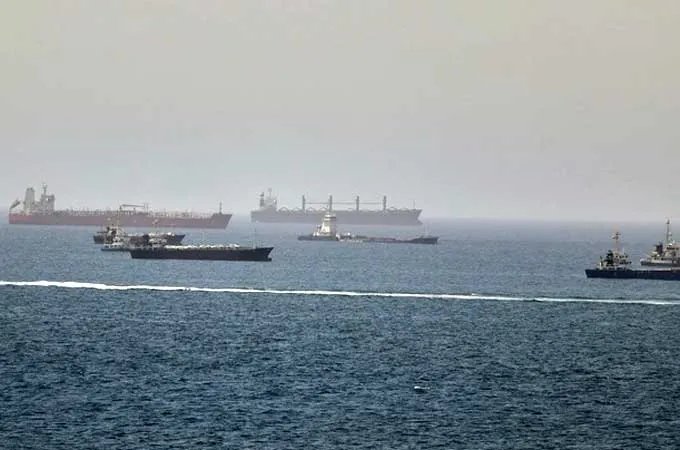
Oil has reflected the impact of regional tensions most directly. Brent crude was trading near $73 per barrel before tensions escalated in the Middle East in late February. Disruption to tanker traffic through the Strait of Hormuz subsequently pushed prices to $120 per barrel in early March.
Since then, oil has moved sharply in response to developments surrounding a potential resolution. With no settlement in sight, tanker flows through the Strait of Hormuz remaining below normal levels and global reserves being drawn down, prices have continued to carry a significant geopolitical premium.
Recent disruption to Saudi Arabia’s Petroline has added further pressure.
Brent has remained above $100 per barrel since September 9, trading within a range of $103 to $109 by mid-month.
"The outlook for oil over the next six months will depend heavily on the direction of the conflict,” Hassan said. “Further escalation around the Strait of Hormuz or Bab Al Mandab, as well as continued Ukrainian strikes on Russian refineries, could increase the risk of a genuine supply shortage and keep prices well above $100 per barrel, particularly while reserves remain low. A durable de-escalation remains the clearest scenario that could bring prices down."
Higher interest rates weigh on gold
Gold, by contrast, has been driven predominantly by interest rates. Because the metal does not generate a yield, it competes with bonds and savings products, which become more attractive as rates rise.
The yield on the 10-year US Treasury crossed 5% this week and touched 5.04%, a level not seen since July 2007, apart from a brief move in 2023.
However, pressure on gold began several months earlier. Hawkish signals from the US Federal Reserve, a strengthening US dollar and persistent inflation readings reinforced expectations that interest rates would remain higher for longer. Together, these factors encouraged investors to move capital from gold into interest-bearing assets.
The result was a substantial correction. After reaching a record of approximately $5,595 per ounce in January, gold declined by around 25% to 30% from peak to trough. It fell below $4,000 in late June, trading at approximately $3,960 to $3,980 per ounce.
Gold has since recovered from its summer low and was trading steadily at approximately $4,310 to $4,350 per ounce by mid-September. The Federal Reserve’s decision on Wednesday to raise rates for the first time in three years has introduced renewed pressure.
“Gold’s direction from here will depend on inflation data and whether the latest rate increase marks the beginning of a longer tightening cycle or is followed by a reversal,” Hassan added. “Persistently high rates and a strong dollar would remain challenging for the metal, while signs of easing inflation and a more accommodative Federal Reserve could restore investor demand.”
Industrial demand continues to support silver
Silver initially benefited from many of the same investment flows as gold, particularly as investors sought protection against persistent inflation and looked to precious metals as stores of value.
Its rally was considerably stronger, however, because it was also supported by industrial demand from the solar, electronics and AI sectors. This combination pushed silver to an intraday record of $121.67 per ounce in late January, while its annual gain reached 173% in May.
Silver has since corrected by approximately 47% from its record high as rising interest rates placed pressure on precious metals. Nevertheless, industrial consumption has helped cushion the decline.
"Unlike investment demand, industrial demand does not necessarily fall simply because bond yields rise," stated Hassan. "Manufacturers still require silver for solar panels, electronics and other advanced technologies. This underlying demand helps explain why silver remains approximately 55% higher than a year ago, despite the recent pullback," he added.
Outlook for the next six months
The outlook for the three commodities will continue to be shaped by different catalysts. Oil is expected to remain closely tied to the conflict in the Middle East and the security of major supply routes. Gold will take its direction from inflation, the US dollar and the Federal Reserve’s next policy moves. Silver will respond to those same monetary forces while also reflecting the strength of industrial orders, stated Hassan.
"Over the next six months, oil will follow the conflict, gold will follow the Fed, and silver will follow the Fed alongside the pace of industrial demand," he added.-TradeArabia News Service