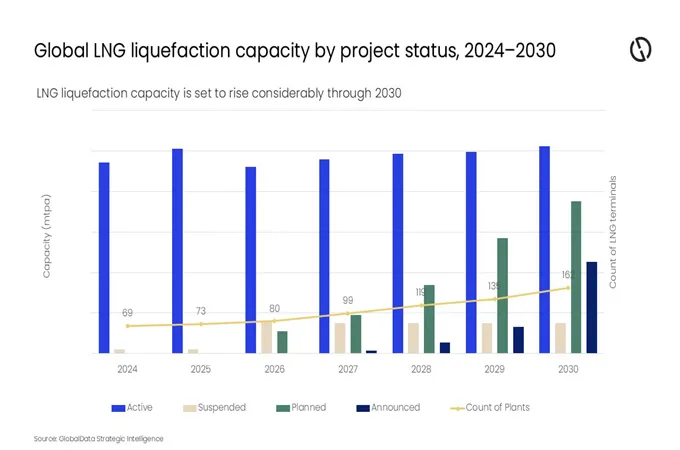
The United States is set to emerge as the biggest beneficiary of shifting global liquefied natural gas (LNG) trade flows amid the Iran conflict, which has disrupted shipping through the Strait of Hormuz and intensified concerns over global energy supply security, according to GlobalData.
The intelligence and productivity platform said geopolitical
tensions are reshaping LNG markets, disrupting supply routes, increasing
freight costs and driving greater price volatility as importers seek more
reliable and diversified sources of energy.
GlobalData’s report, “LNG Industry Landscape,” forecasts
global LNG liquefaction capacity to increase from 482 million tonnes per annum
(mtpa) in 2024 to around 874mtpa by 2030, based on projects in advanced stages
of construction.
Meanwhile, global regasification capacity is expected to
rise from 59,378 billion cubic feet (bcf) to more than 77,800bcf, led by
expansion in Asia and Europe.
Ravindra Puranik, Oil and Gas Analyst at GlobalData, said:
“Geopolitical tensions are materially reshaping the global LNG landscape by
tightening supply options, re-routing trade flows, and elevating price
volatility across key consuming regions. The war in Ukraine has been the
central shock, accelerating Europe’s structural pivot away from Russian
pipeline gas and toward seaborne LNG, which in turn has increased Europe’s
reliance on global spot cargoes and reduced supply flexibility for
price-sensitive importers.”
Although Iran is not a major LNG exporter, the conflict has
disrupted regional energy production and shipping continuity. The disruption to
traffic through the Strait of Hormuz has raised concerns over the reliability
of LNG supplies, with markets factoring higher risks into freight rates, vessel
availability and spot procurement costs.
The conflict has also highlighted the vulnerability of
Qatar's LNG exports, with capacity equivalent to around 12.5 per cent of global
liquefaction affected, further intensifying competition for available cargoes.
North America, led by the US, has the world's largest
operational LNG liquefaction base at 132mtpa, alongside 159mtpa of capacity in
advanced development and another 151mtpa in earlier development stages, some of
which could become operational by 2030.
US LNG supplies are particularly well positioned because
Henry Hub-linked volumes operate outside the Strait of Hormuz and offer
flexible destination terms. This gives American exporters an opportunity to
redirect cargoes towards Europe and Asia as buyers seek alternatives.
European regasification terminals are expected to see higher
utilisation as the region competes for flexible LNG cargoes, potentially at
premium prices. In contrast, price-sensitive South Asian and some Southeast
Asian markets could experience lower terminal utilisation due to higher import
costs and affordability constraints.
Puranik concluded: “Overall, the combined effects of the Ukraine and Iran conflicts are reinforcing a more risk-aware LNG market characterized by higher premiums for reliability, greater competition for marginal cargoes, and a continued emphasis on policy-aligned, resilient supply chains.” -OGN/TradeArabia News Service