Bahrain’s proposed 10 per cent corporate income tax, which would apply to businesses exceeding specified revenue or taxable profit thresholds, came under parliamentary scrutiny yesterday, with MPs stressing the need to protect the competitiveness of national companies while ensuring sustainable government revenues, a Gulf Daily News report said.
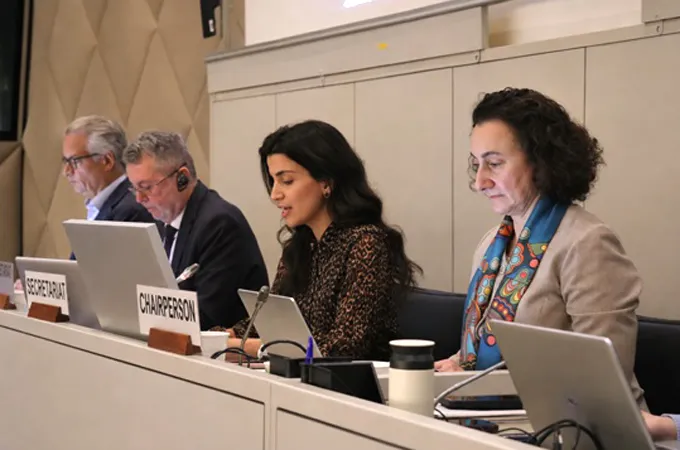
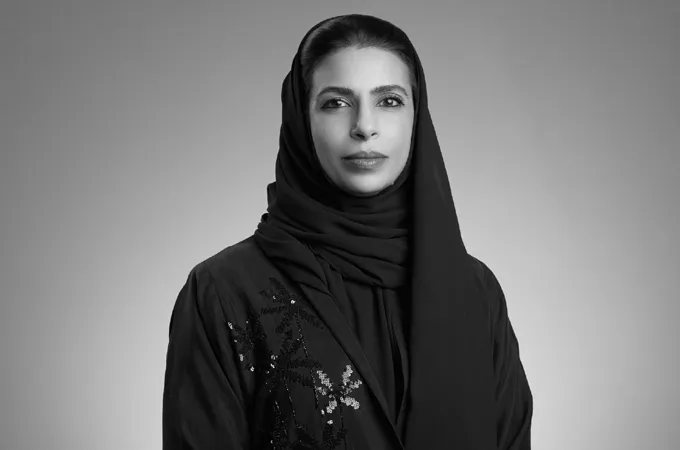
Parliament’s financial and economic affairs committee, chaired by Ahmed Al Salloom, discussed the draft law accompanying Decree No 79 of 2025 during a meeting attended by National Bureau for Revenue (NBR) chief executive officer Rana Faqihi and her accompanying delegation.
Al Salloom said the proposed legislation required comprehensive economic assessment and further clarification before the committee could finalise its report and submit its recommendations to Parliament.
“We must fully understand the implications of introducing corporate income tax, particularly its impact on national companies, the competitiveness of our economy and the ability of private businesses to expand, attract investment and create employment opportunities for Bahrainis,” he said.
He stressed that legislators needed to establish whether the proposed framework would achieve the right balance between diversifying and sustaining public revenues and preserving the attractiveness of Bahrain’s business environment.
The proposed tax would represent a significant shift in Bahrain’s business taxation system, under which most companies have traditionally operated without general corporate income tax, apart from businesses in the oil and gas sector.
Under the draft legislation, the main provisions include:
* 10pc corporate income tax on taxable profits exceeding BD200,000.
* BD1 million annual revenue threshold: Companies exceeding this revenue level would fall within the proposed tax regime.
* BD200,000 profit threshold: Companies with taxable profits exceeding this amount would also be covered, even if their annual revenues were below BD1m.
* January 1, 2027: The proposed implementation date for financial years beginning on or after this date, subject to legislative approval.
* Exemptions: Certain income categories, including qualifying dividends, specified capital gains, government grants and certain activities, are covered by proposed exemptions.
The 10pc rate would apply to taxable profits exceeding BD200,000, rather than the company’s entire turnover. The proposed framework also covers qualifying resident businesses and certain non-resident businesses operating through permanent establishments in Bahrain.
The legislation is expected to be administered by the National Bureau for Revenue, with further implementation details to be addressed through executive regulations.
Al Salloom said the committee’s discussions with Faqihi were aimed at obtaining a clearer understanding of the proposed tax framework, its implementation requirements and its wider economic consequences.
He stressed that the interests of national companies, particularly their ability to remain competitive, expand operations and generate employment for Bahrainis, must be carefully considered alongside the government’s revenue requirements.
The committee will continue examining the legislation before finalising its report and submitting its recommendations to Parliament.